What a portfolio is
A portfolio is a named group of slots. Each slot pins one saved strategy to one broker account with a size multiplier.
The same strategy can appear in several slots — once per account — and one account can carry several strategies. A supervisor checks every active portfolio about every 15 seconds: it launches active slots that have not run today, counts what is live, and watches the group's combined P&L against its cap.
Strategies you assign directly, without a portfolio, sit in a built-in "Direct Deployments" group that carries no portfolio-level caps.
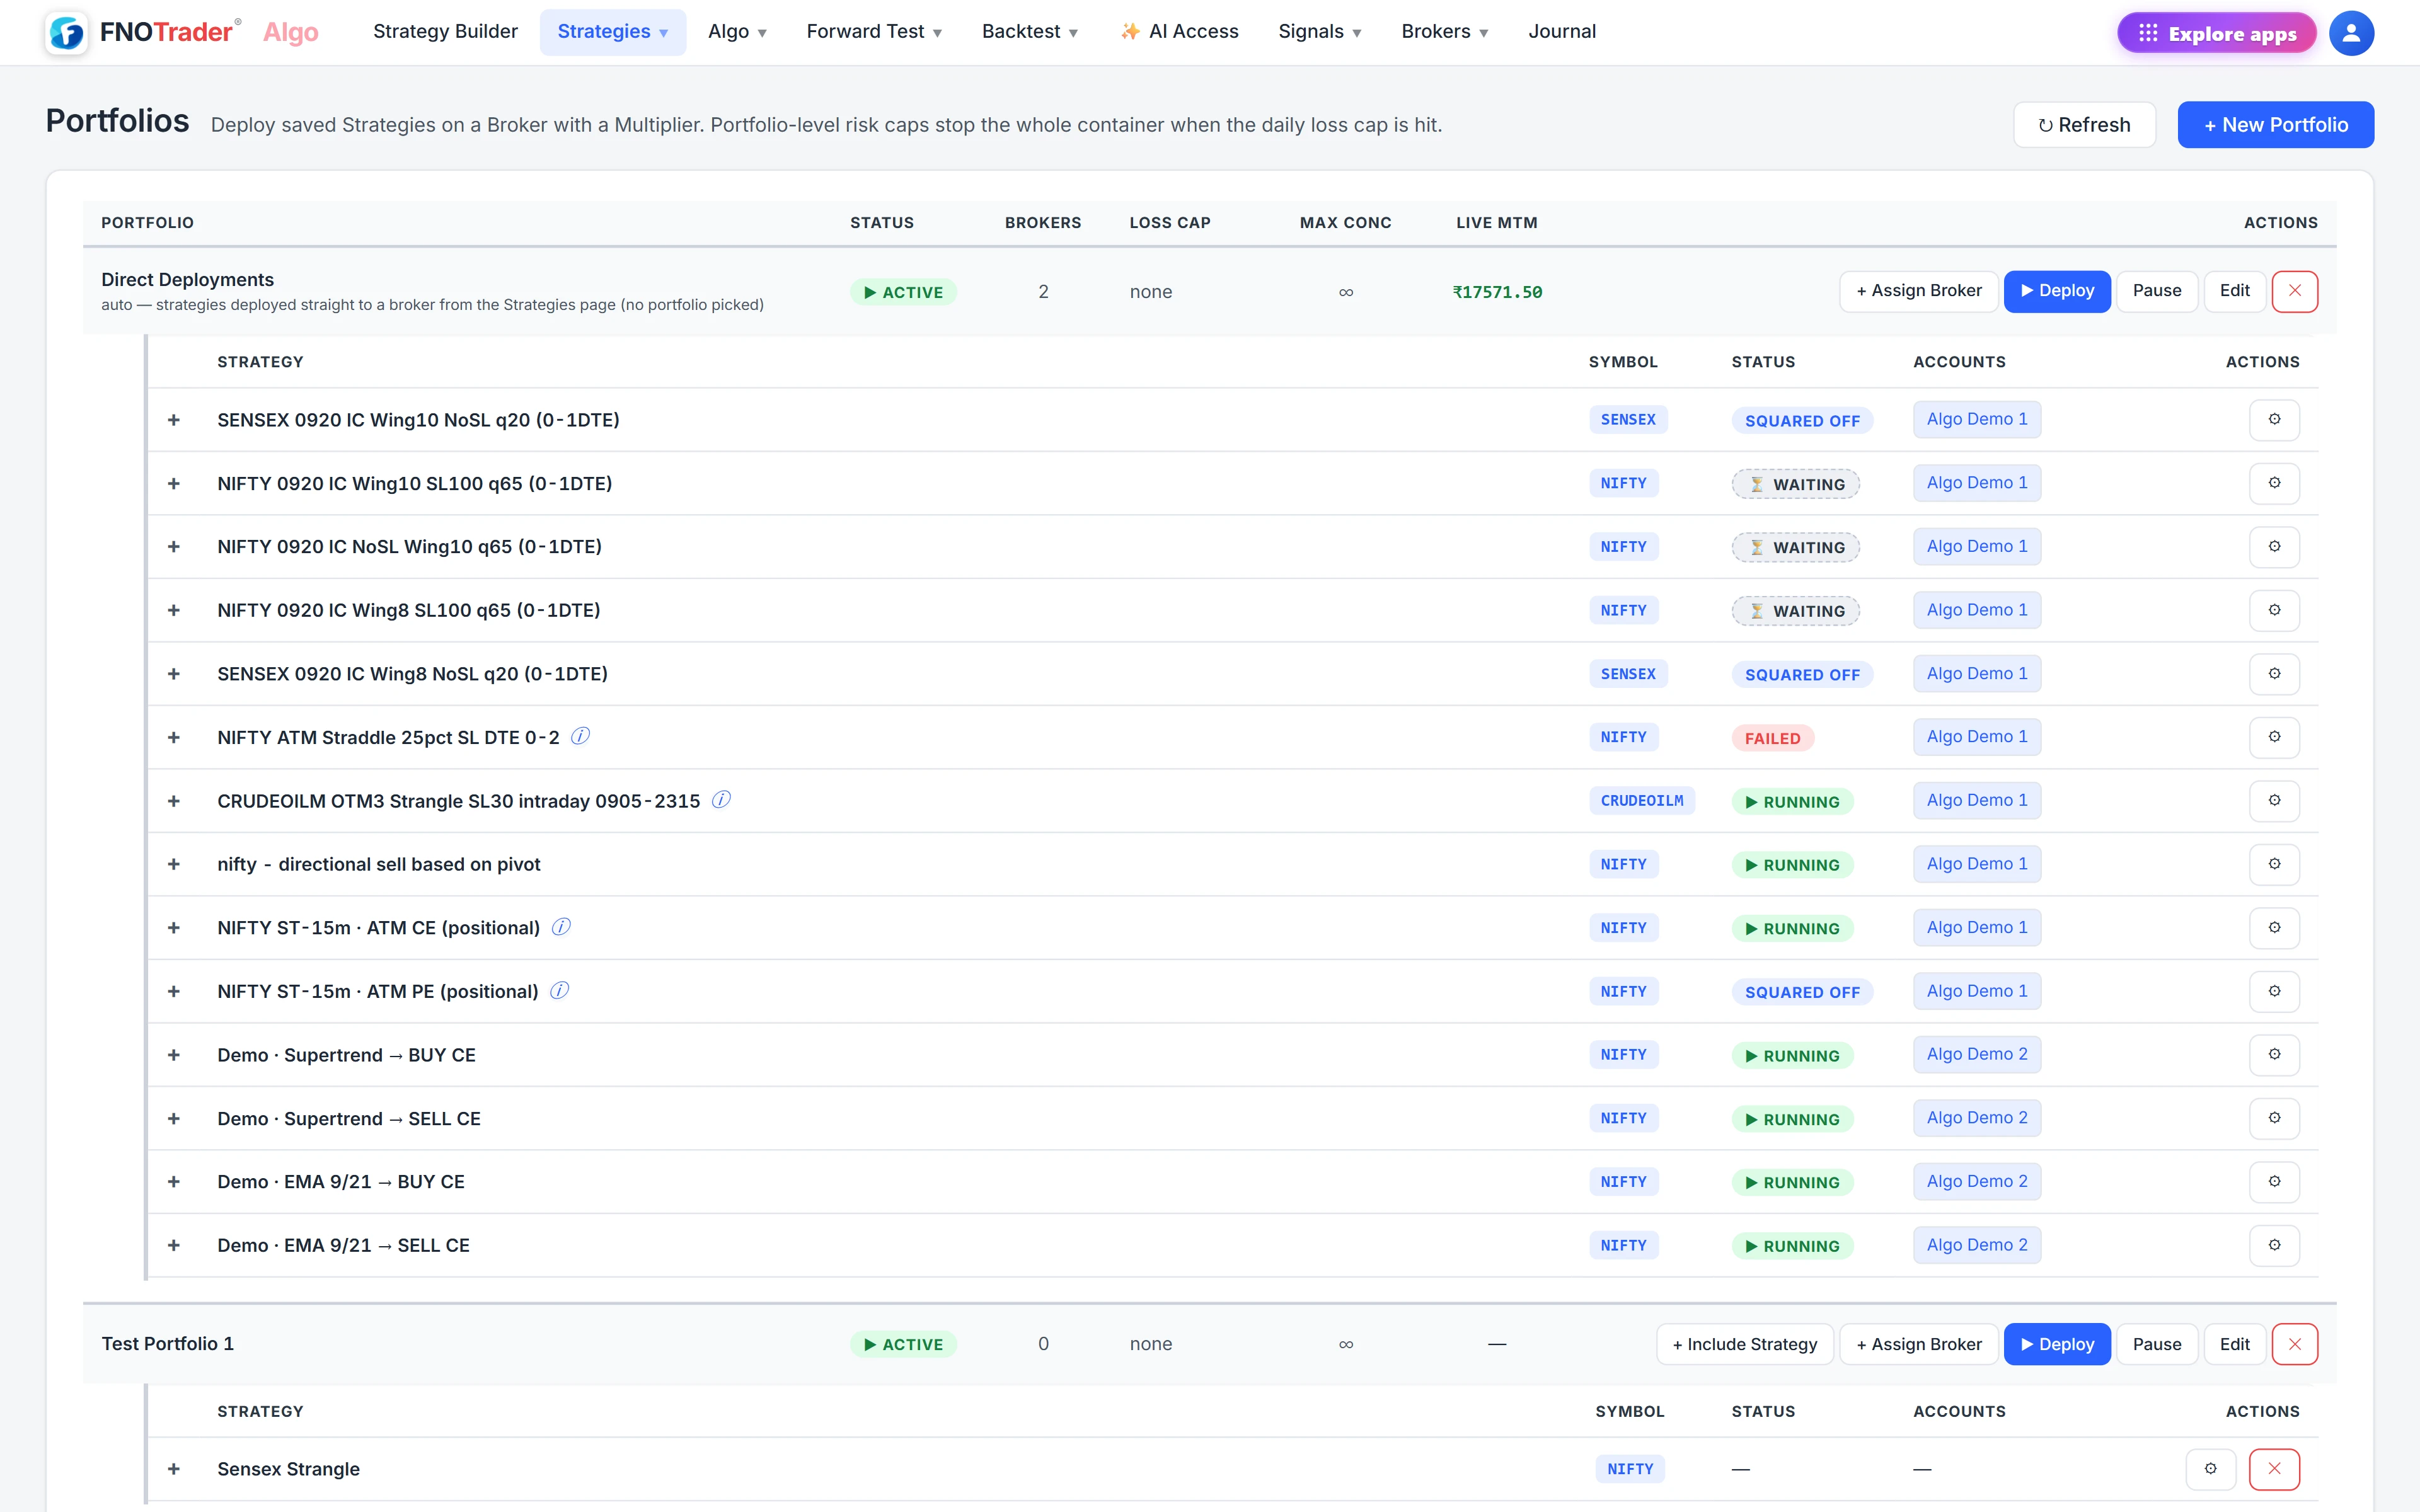
The settings
| Setting | What it does |
|---|---|
| Slot: strategy × account × multiplier | Which strategy, on which account, at what size. Each slot can be switched on or off on its own. |
| Daily loss cap ₹ | When the combined P&L of the portfolio's runs today falls to −cap, every run in it is squared off and none relaunch until IST midnight. |
| Max concurrent strategies | Once that many are live, further slots wait instead of launching. |
Each slot launches at most once per IST day. A run that started today — even one that has since been stopped out or blocked by its own day filter — holds its slot until midnight, so the same signal is never entered twice and live stays in step with how the backtest counts days. A slot that keeps failing to launch is parked for the rest of the day with one notification, and the reason shows on the slot.
What the multiplier scales, and what it does not
The multiplier scales anything that is about size:
- each leg's quantity in lots, rounded down and never below 1;
- the basket's ₹ stop-loss and target;
- ₹-based stop and target rungs on legs and on the basket.
It leaves alone anything that is not about size — percentage, points, underlying move, ATR and delta based rules — because a 30% stop means the same thing at any size. Not every ₹ figure in a strategy scales, so after setting a multiplier, open the strategy and check each ₹ threshold against the size it will actually trade.
Keep size in one place. A strategy built at 17 lots and linked at ×17 trades 289 lots, which can exceed the exchange freeze limit and fail.
A worked example
A hypothetical portfolio has two slots for the same strategy (3 lots per leg, basket stop ₹6,000): Account A at ×1 and Account B at ×1.5. A third slot runs a second strategy on Account A. Daily loss cap ₹25,000; max concurrent 2.
- Account B trades 3 × 1.5 = 4.5, rounded down to 4 lots, with a basket stop of ₹6,000 × 1.5 = ₹9,000.
- With two slots live, the third waits until one finishes.
- At 13:00 the two live runs show −₹14,000 and −₹11,500: combined −₹25,500, past the cap. Both are squared off and nothing in the portfolio launches again that day.
Note that rounding means Account B is sized at 1.33×, not 1.5×, while its stop is scaled by the full 1.5×. Use multipliers that give whole lots.
Backtesting a portfolio first
The Backtest page has a Portfolio mode that replays every strategy in the portfolio over the same dates, each on its own underlying, and combines them into one equity curve and drawdown — see running a backtest. A combined drawdown is often smaller than the sum of the parts, and sometimes larger when strategies lose on the same days; the combined report shows which.
Where to find it
- In Algo, open Portfolios and create one.
- Add slots: choose a strategy, an account and a multiplier.
- Set the daily loss cap and max concurrent strategies.
- Monitor it under Algo → Portfolios (live) or Forward Test → Portfolios (demo), where the portfolio's logs also show blocked launches.
- Account-wide limits that apply across portfolios are on the Risk page — see risk and the kill switch.
Common questions
How does the portfolio multiplier work in Algo?
It scales each leg's lot count (rounded down, at least 1) and the basket's rupee stop and target. Percentage and point-based rules are not scaled, because they do not depend on size.
What happens when a portfolio hits its daily loss cap?
Every running strategy in that portfolio is squared off and none of its slots launch again until IST midnight.
Can one strategy run on several broker accounts?
Yes. Add one slot per account, each with its own multiplier, in the same portfolio.
Why didn't my portfolio slot relaunch after it was stopped out?
Each slot launches at most once per IST day. A run that started today holds the slot until midnight, which prevents re-entering on the same signal.
More on Algo & Backtesting
More in Algo & Backtesting · App: Algo & Backtest · Definitions: glossary · All: every article