What a forward test is
In Algo a forward test is not a separate kind of object. It is your saved strategy assigned to a Demo (paper) account instead of a real broker account.
It runs on the same live option chain and the same strategy engine a real deployment uses. The only difference is the account: orders go to a simulated book instead of a broker. Entry conditions, stops, targets, trailing, re-entries, adjustments and square-off all behave as they would live, on live prices.
That makes it the honest test of everything a replay approximates — second-by-second timing, strikes chosen from today's chain, and instruments with no backtest history, such as MCX commodities.
How paper fills work
A demo account starts with a large notional balance (₹1 crore by default). When the strategy sends an order, it is filled immediately at the live price at that moment and stored like a real order: the order book, trade book and positions are built from those fills, and round-trip P&L is matched first-in-first-out.
Two things follow. First, a paper fill has no queue and no partial fill; your broker's real fill can be worse, especially in thin strikes. Second, a protected market order is filled at the live price, not at the protective limit, so positions do not open in the red because of the buffer.
Because fills are instant, a resting order cannot be modified or cancelled on the paper book — there is nothing pending to change.
What to compare, and how long to run it
Run a forward test long enough to see the strategy's normal behaviour, not just a good week. Then compare three things against the backtest for the same days:
| Check | What a mismatch means |
|---|---|
| Did it trade on the same days? | A gate (time window, DTE, gap, signal) behaves differently live than you assumed. |
| Did it pick the same strikes? | Dynamic strike rules resolve differently on live premiums or greeks. |
| Are stops firing at similar points? | Live ticks see spikes a 1-minute bar compresses. Live can act up to a bar sooner, never later. |
A forward test that matches the backtest on trades but not on P&L is usually telling you about fills and friction. One that does not match on trades is telling you about the rules.
A worked example
A hypothetical strangle backtests at an average of ₹600 a day after costs and slippage. After four weeks of forward testing it averages ₹450.
You run a backtest over exactly those four weeks. It shows ₹520 a day, and the same entries on the same days. The gap from ₹600 to ₹520 is simply that these were weaker weeks; the gap from ₹520 to ₹450 is timing and fills, about ₹70 a day. If ₹70 a day is larger than the slippage you set, raise the slippage setting so future backtests reflect it.
What a forward test does not prove
- Paper fills are instant at the live price. Liquidity, rejections and partial fills are real-account effects.
- A few weeks is a small sample. Read the result next to the Monte Carlo range, not instead of it.
- A forward test does not need a broker login, so it will not reveal a broker that is logged out at 09:15. That is covered in running live.
Where to find it
- From a finished backtest report or a Backtest History row, click Forward test. Or open Strategies in Algo and assign the strategy to a Demo account.
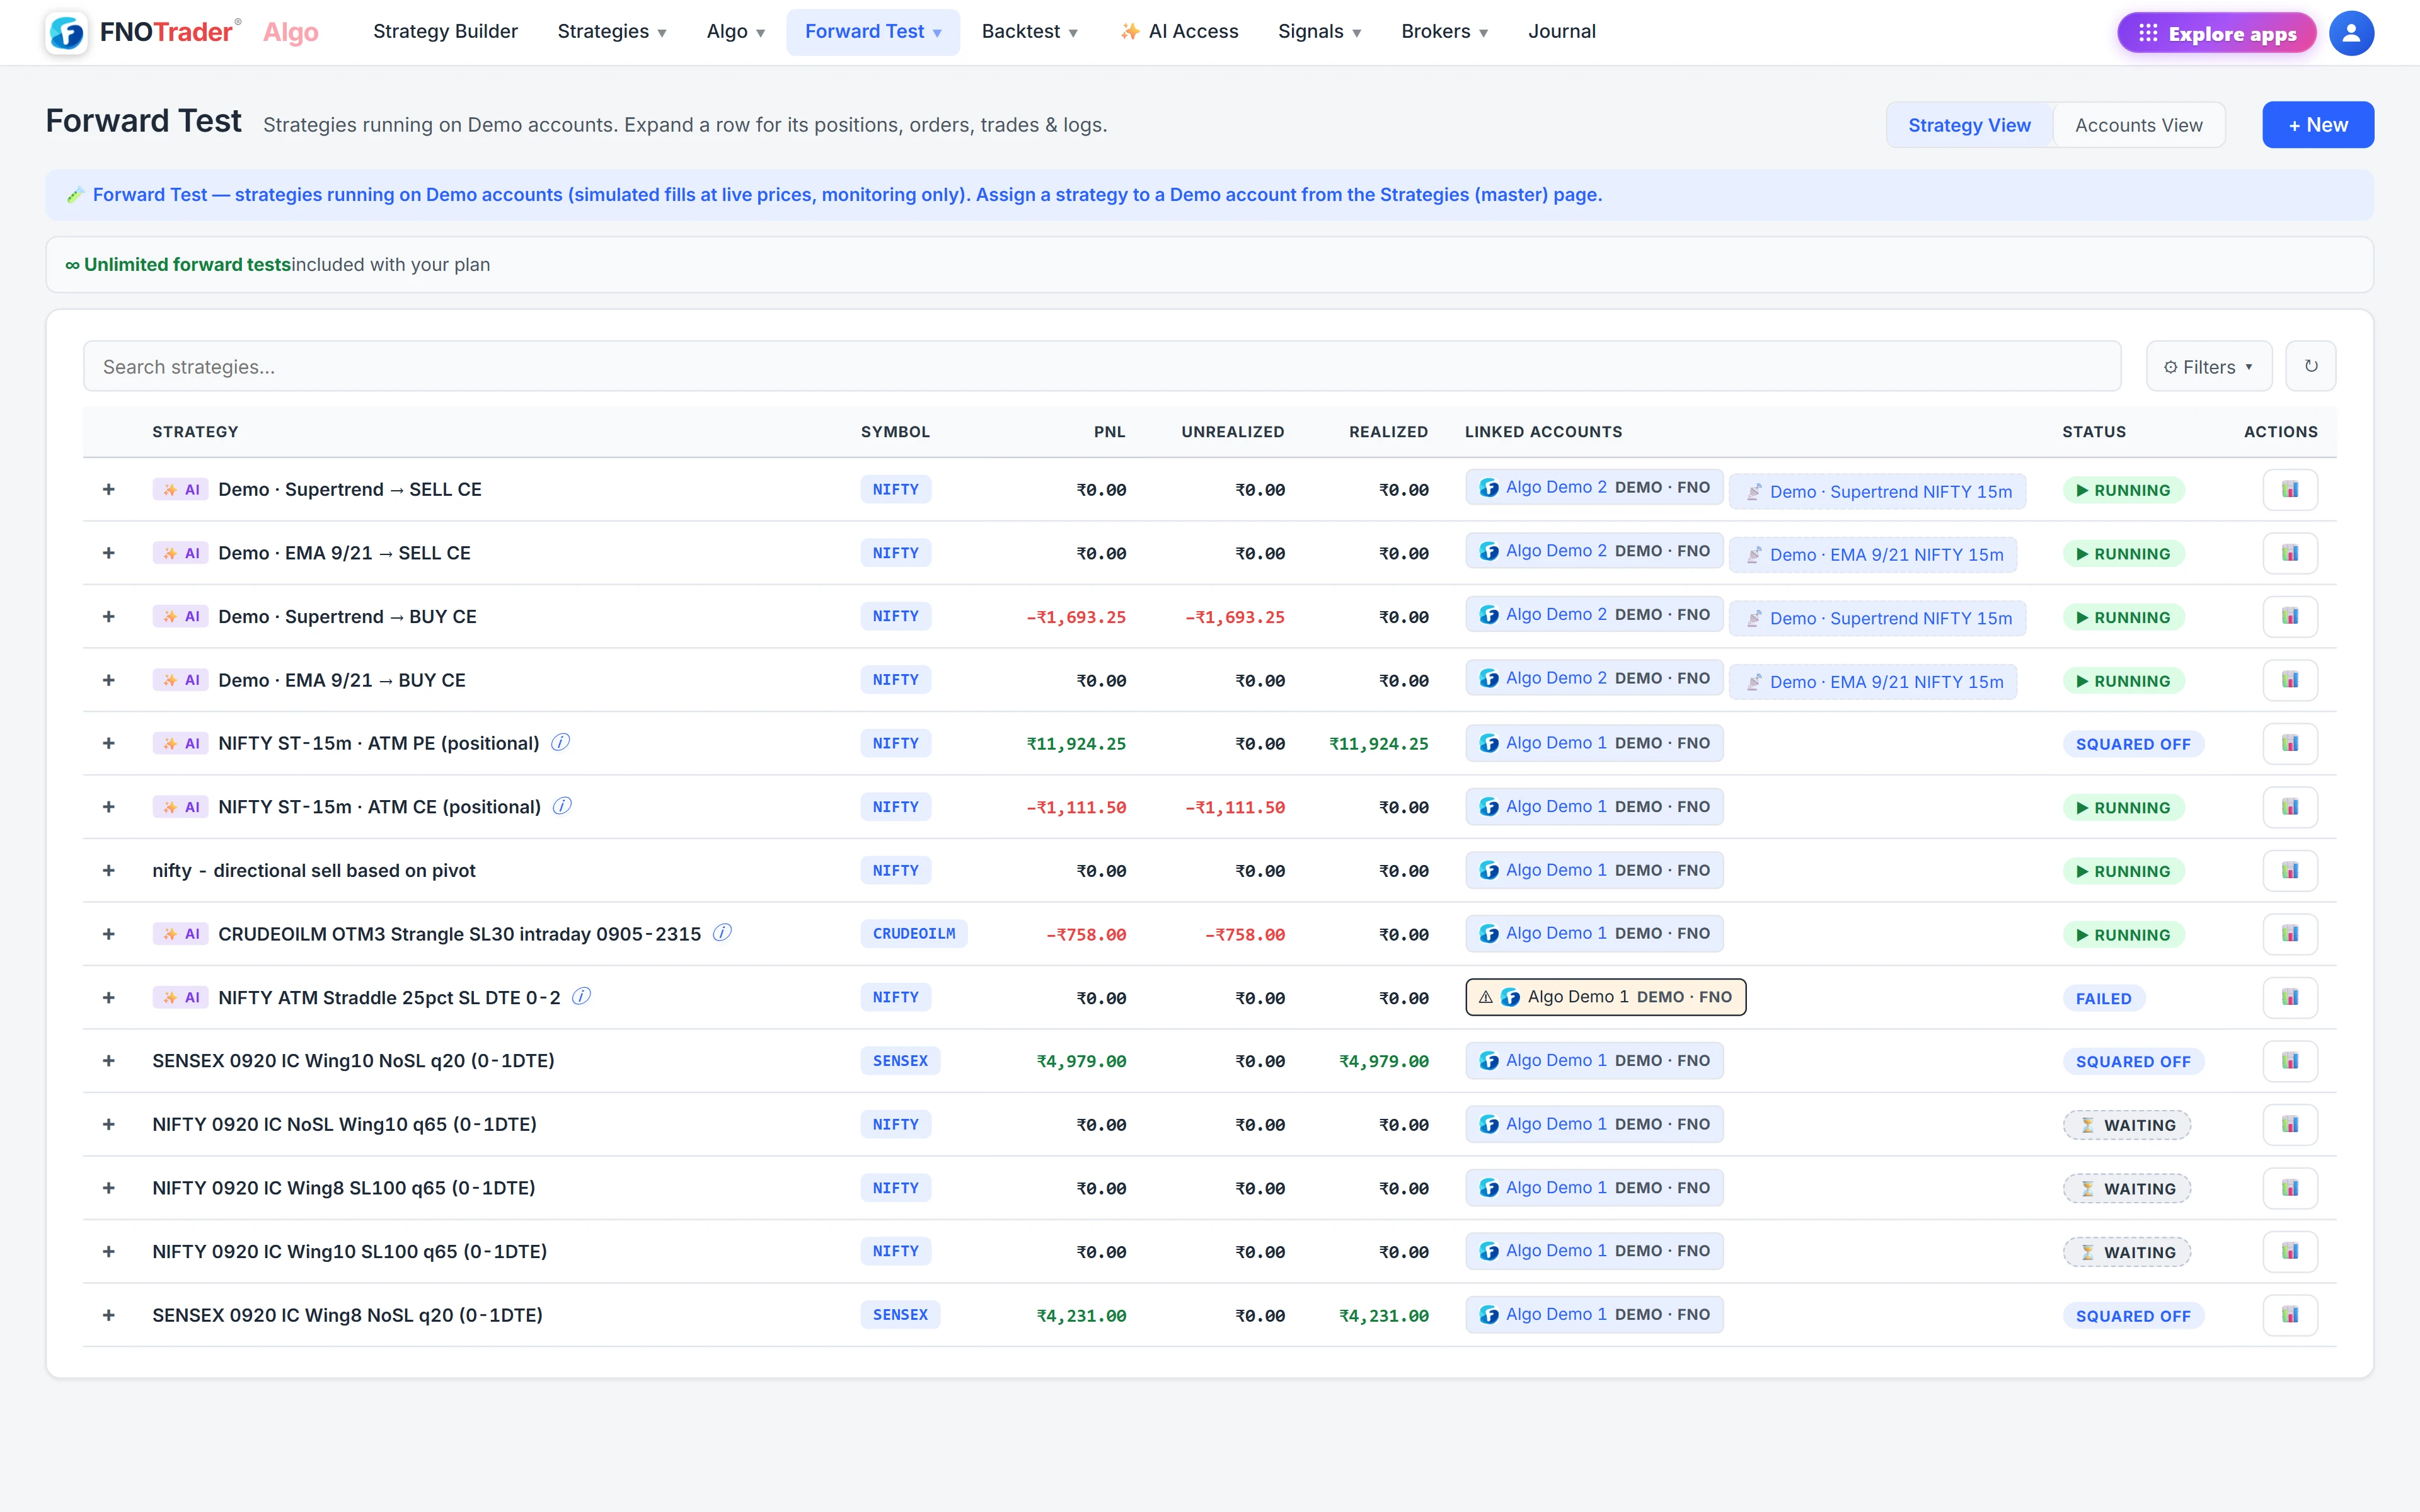
- Watch it under Forward Test → Strategies. Expand a row for Positions, Orders, Trades and Logs.
- Review results in the Forward Test Journal — see the Journal.
Common questions
What is the difference between a backtest and a forward test?
A backtest replays a strategy on historical 1-minute bars. A forward test runs it now, on live prices and the live chain, against a demo account, so timing and strike selection are real while no money is at risk.
How are paper trades filled in a forward test?
Immediately, at the live price at the moment the order is sent. The orders, trades and positions are stored like a real account's, and P&L is matched first-in-first-out.
Can I forward test MCX strategies?
Yes. MCX has no backtest archive, but a forward test runs on live prices, so it works for MCX and any other underlying the builder supports.
Does a forward test use the same engine as live trading?
Yes. It runs the same strategy engine on the same live chain. Only the account differs, so the result reflects your rules as they would actually execute.
More on Algo & Backtesting
More in Algo & Backtesting · App: Algo & Backtest · Definitions: glossary · All: every article